

Yang Chisheng: How to build a risk defense system in a difficult environment
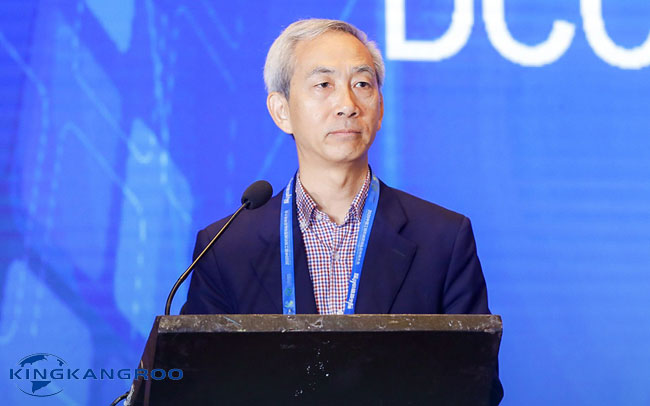
Yang Chisheng
Executive Vice President of Agent Working Committee of China Construction Machinery Industry Association
Chairman of Beijing Hengri Construction Machinery Co., Ltd.
Risk is both a threat and an opportunity.
To actively respond to risks and challenges, enterprises need to work hard, and business operators need certain experience.
Be "firm, calm, and calm" in "addition, subtraction, multiplication, and division": a firm belief in the long-term improvement of the general trend of construction machinery, and the necessary calmness in dealing with various difficult situations during the market downturn, especially when risks are intensified. Effective business thinking and self-calmness in the implementation of adjustments in market fluctuations.
After the profound lessons of the previous cycle, we carefully reviewed our own capabilities and required all business boundaries to be within the scope of our own strength, including risk prevention and management.
At any stage, the key to coping with the risks brought about by the market downturn depends on whether the enterprise is ready. To avoid risks, the earlier you do it, the fewer problems you will face later.
For enterprises, the crisis has already emerged, and turning the tide may not be the best way to resist risks. Take precautions in advance so that you will not be overwhelmed when a crisis comes. More importantly, if you take the initiative to establish a defense system, gradually build, continue to build, and maintain your own immune system for a long time, your ability to resist risks will naturally be stronger than others.
Correctly understand the "change" and "invariance" of risks
Sizing up the situation and fighting a prepared battle to prevent, control and defuse risks.
From the perspective of risk itself, if the risk in the previous cycle was more due to the outbreak of credit risk caused by low customer quality, poor customer reputation, and disappearance of people and vehicles, the current risk is the profitability caused by blindly and brutally fighting price wars. The decline, the risk of breaking the capital chain.
In the same downward range, the profits of mainframe manufacturers have improved, but many agents have not made any money, or even lost money. The main reason is the lack of core competitiveness.
In this round of cyclical downturn, the risk of creditor's rights presents two relatively optimistic characteristics: one is that there are not many overdue amounts, and the other is that customers' awareness of credit has increased and they are afraid of breaking their promises. Therefore, it is easier for customers to cooperate in handling creditor's rights. In this round of cycle, most of the customers who are overdue are really out of money. If they can’t receive the project or can’t get the project money back, there are very few malicious arrears.
Generally speaking, although there is pressure now, the risks are still controllable. However, there may be a large-scale outbreak of customer overdue in the second half of this year or next year at the earliest.
For some domestic brand agents, this wave of debt risks may be as serious as the previous cycle: price wars are inherently losing money, and accounts receivable cannot be returned, and there is no stock, and there is no It is difficult to have income from services.
"Many of us have survived such dark nights, so we should know how to cherish the precious days."
At present, nearly 40% of Beijing Hengri's customer orders are sold in full, with almost no overdue. Incredibly, the company's market share has also exceeded the average share of manufacturers.
Practice has repeatedly proved that risk control requires analysis and judgment of the enterprise's living environment and industry development situation, and assessing the situation. What is more important and difficult to achieve is to strictly abide by the bottom line, focus on refined internal management of the enterprise, and shift more risk response after the event to risk prevention before the event.
Move the prevention and control forward and strictly control the credit risk
It is necessary to do preliminary work, and the cost of remediation in the later stage will be very high.
If you want to avoid risks, you must start from the source. In terms of customer credit management, do the work ahead.
Some agents said that the credit management is particularly good, and the debt management and control is particularly good, which refers to the good situation of the industry. Before we do this now, what we consider is whether the customer has the ability to repay the loan on schedule when the market is not good? What possible responses can we take?
The review of credit must be strict and standardized. Before sales, customer authenticity investigation, qualification review, asset and equipment mortgage, and mandatory notarization must be done.
Whether there is repayment ability, whether the guarantor is qualified enough, whether there is collateral, how is the character and reputation, working experience, operating ability, social relationship, mortgage situation, risk tolerance, upstream project payment status, etc., these conditions should be Carefully implement, strictly control, and fully grasp.
Beijing Hengri has specially built a set of credit management scoring system and historical database to centralize and coordinate the management of key customer information, use these data to classify and build files for customers, track customer credit evaluation, and focus on dynamic monitoring of risks that may arise at any time for high-risk customers Changes, large customers set up special agencies to maintain. Break the information asymmetry between departments with fast uploading and high sharing of information, make risk warnings in advance, improve business efficiency, and reduce communication and management costs.
Credit checks are never child's play, but are often overlooked. When many agents complain that they encounter customers with bad credit, few people look back and reflect that the risk is largely due to insufficient initial investigation work and lax checks. If the customer's qualifications are carefully and accurately evaluated and assessed in the early stage, the probability of problems can often be reduced.
The risk may only come from an inadvertent link, but it is the entire enterprise that is affected. In the same way, risk management and control is not aimed at a single business link, nor can it be completed by a single department. It is a systematic project that requires coordination and overall planning.
Departmental linkage to improve the risk sharing mechanism
It is necessary to guarantee from the system and the process, so that the products that everyone is unwilling to sell from the subjective consciousness have problems.
Generally speaking, the sales department requires performance and gets bonuses, while the debt department emphasizes risk prevention and credit control. Due to differences in the division of responsibilities and performance orientation, it is inevitable that there will be a game between left and right. There is a common phenomenon that business and risk control performance assessment deviate.
However, the sales staff only sell the cars without collecting the bills, and the creditors do not understand the customers and only press for payment. The imbalance between business and risk control is not conducive to the effective operation of the enterprise. Not enough attention is paid to the risks in the sales process. Once a problem occurs, the creditor's rights department will spend a lot of manpower, time and energy on overdue collection and legal proceedings. The risks are endless and the gains outweigh the losses.
In essence, the interests and goals of the two are the same. What enterprises really need is a business that can bring profits and cash flow, not a business that is exchanged for high leverage and accumulation of accounts receivable.
In view of this, it is necessary to further improve the internal process control mechanism and value evaluation and assessment system, break departmentalism, integrate resources, improve personnel's risk and legal awareness from the subjective level, and clarify rights, responsibilities, and risk sharing. Cultivate the risk control literacy of sales personnel, let risk control personnel strengthen business orientation, realize the value balance of personnel in different positions, and achieve both business excellence and risk control.
Beijing Hengri has always emphasized co-creation, sharing, and joint responsibility, and adheres to the three-party risk sharing of business departments, creditor's rights departments and the company in risk management and control. Propose valuable discussions on potential risk points in advance and carry out targeted prevention. If there is a problem with payment, each will bear one-third of the loss. To clarify responsibilities and burdens, we must have process and system awareness from the very beginning. It is inevitable and unavoidable. Through the transmission of pressure, we can ensure that there are no problems from both objective conditions and subjective psychology.
We said that rewards and assessments are only supplementary. The key to the problem is to give full play to people's subjective initiative to establish a sense of urgency and assist enterprises in establishing risk control awareness.
In the coming period, we will face a more complex external situation and a more difficult market environment, and we must be fully prepared to deal with various difficulties.
Stick to the bottom line, take the initiative to control the risk
Risks are full of challenges, and may also be related to the survival and transcendence of the enterprise.
While the market is shuffling the cards, it is also shuffling people, their thoughts and concepts. With the decline of the market, risks began to appear and gradually exploded. At this time, it is not too late to shift the focus to risk control.
The group of Chinese construction machinery agents has been baptized for many rounds, and they should have accumulated certain experience, and have grown and improved in risk management and response capabilities, but it is far from enough.
"Exchanging sales with guarantee" and "exchanging scale with profit" seem to be issues of creditor's rights on the surface, but in essence they are related to the business philosophy and internal management of the enterprise. What lies hidden in this is the structural risk of the original business model.
In the face of changes and risks, it is doomed to have no solution if we apply the original model again. Structural risks require deeper changes. Excellent companies must insist on changes, and then slowly affect and drive changes in the entire industry. Just like a "price war", although you can't influence other people's choices, you can use your own actions to influence others.
The agent's risk management and control should be determined by the agent himself and borne by himself. Enterprises that pursue long-term valueism pay more attention to the standardization and legality of their own behavior, because this is the premise of safeguarding their own rights and interests.
"Customers with bad credit, orders that can't recover the cost, insist on not doing it, at least I am healthy, can survive, and keep the achievements made in the past."
Agents should focus on improving lean management and risk control, and maintain profitability to have core competitiveness (creating value for customers). Conversely, in the process of market competition, powerful agents have the initiative to select high-quality customers and reduce hidden risks at the same time.
In the stock market, the focus is on the screening and maintenance of high-quality customers. More importantly, we must fully grasp customer needs, truly solve customer problems, and make the remaining business real, deep and strong, and the accessories and aftermarket can also be developed into strategic businesses.
Adhere to valueism and return to the origin of value. I hope that everyone will not forget their original aspirations, survive in the midst of changes, and still maintain a sense of self-examination.